Why are interest rates so low?
There was a time between the late 1970s and early 1990s when it was usual for interest rates to be in double figures. Many older home owners now remember it with horror because it meant mortgages were very expensive things to have.
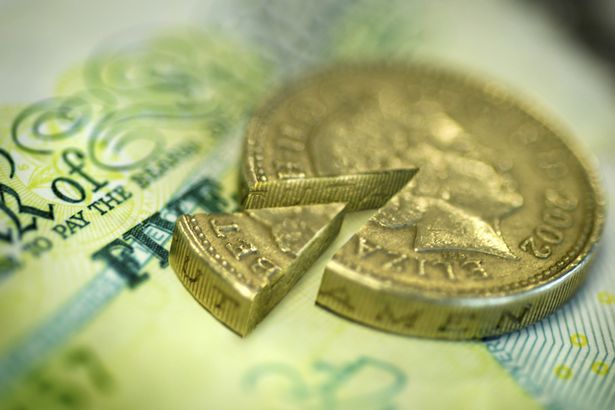
But since 2008 and the global financial crisis most western governments including the UK's have used very low interest rates to stimulate the economy by making it cheap to borrow money. This is good for businesses, who can access cheap funds to grow their businesses and for home buyers.
In August last year the Bank of England cut the base lending rate from 0.5% to 0.25% and mortgages have followed suit. For some time now mortgage rates for three-year fixed rates with a 10% deposit, for example, have been hovering just under 3%. Two decades ago it was just over 7%.
Why did they do it?
August's change was the first rate reduction since 2009 so the Bank didn't take the decision lightly. It was prompted by the economic uncertainty which has followed the result of the EU referendum in July.
Along with cutting interest rates, the bank also announced they would be putting money into the economy through a strategy known as quantitative easing. Basically, the bank buys government bonds to boost the economy.
Why it's good for aspiring homeowners
Last year's reduction in interest rates means even more affordable mortgages are becoming available. You still have to meet the eligibility criteria of course, which is where Credit Ladder can help, and prove you can make the repayments. But, if approved, the cost of your mortgage will be lower.
Several building societies have already announced rock bottom deals on ten year fixed loans and, with further cuts in interest rates being expected, even better deals will be on the horizon for both fixed and variable rate mortgages.
What you can do now
As a registered user of Credit Ladder you have already taken the first steps to becoming a 'good risk' for mortgage companies. Your monthly rental payments are already helping to increase your credit score and appearing in your credit report.
If you aren't currently registered with Credit Ladder visit this page www.creditladder.co.uk to see how the scheme works. You will discover how you can increase your credit score simply by continuing to make your normal monthly rent payment.
To ensure you will be in the best possible position to take advantage of the new mortgage deals which are coming on stream, make sure your credit report is accurate and, if you are making repayments on loans or credit cards, make sure they are made on time and to schedule.
See our articles on How to check your credit score https://www.creditladder.co.uk/blog/check-your-credit-score and 5 tips on how to improve your credit score https://www.creditladder.co.uk/blog/improve-credit-score-quickest-ways for more information.
Remember, CreditLadder can help you improve your credit score.
CreditLadder can improve your credit position by reporting your rent payments. CreditLadder is the first way to improve your credit score and position across all three of the main Credit Reference Agencies in the UK, namely Experian, Equifax and TransUnion. Building up a high credit score has a lot of benefits, including helping you access finance at better rates - this can also help save you money. CreditLadder also runs a free mortgage application service in partnership with Tembo which will tell you how much you could borrow.
Remember the content provided in this article is for information purposes only and should not be considered as advice.